Economics & Logistics
Composting competes with land application of raw manure, sale of feedstocks, or simply paying to dispose of them. The ledger differs by scale — here are the moving parts.
The economic frame
For most livestock farms the comparison is not "compost vs nothing" — it's compost vs raw manure handling. Composting adds process cost (bulking agent, turning, pad, labor) and returns a lighter, drier, odor-reduced, P-concentrated, more marketable product, plus avoided costs (bedding purchases, spreading tonnage, neighbor/permit friction). Whether it pays depends on:
- Volume and distances: more material and longer hauls favor composting (water you don't haul is money you keep).
- Existing equipment: a loader and pad put you most of the way; a dedicated turner changes the labor math at scale.
- Market proximity: landscaping, nursery, and garden markets within an hour's haul can turn compost from cost center to product.
- Regulatory position: some jurisdictions treat composting more favorably than daily raw-manure spreading; others require permits that add cost.
Cost structure
| Cost item | Typical on-farm range (indicative) | Notes |
|---|---|---|
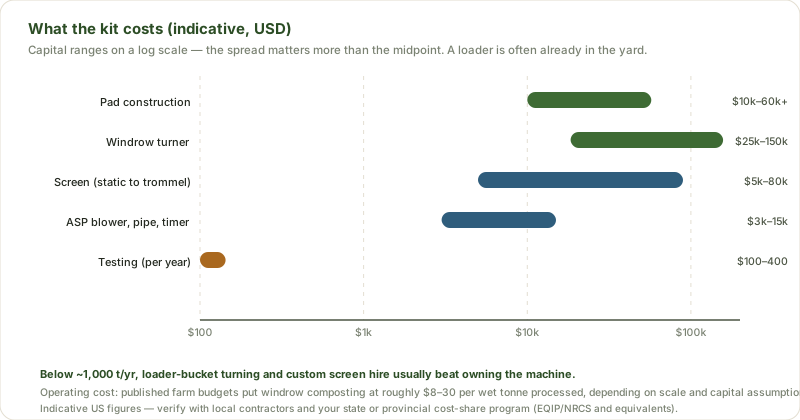
| Pad construction | $10k–60k+ (or $0 if existing concrete/gravel) | Single largest capital item; drainage drives the price |
| Windrow turner | $25k–150k (tractor-mounted to self-propelled) | Loader bucket turning is viable below ~1,000 t/yr |
| Loader | Often already owned | The universal tool; size for the bulking agent handling |
| Screen | $5k–80k (static to trommel) | Only needed for sale/mulch markets; custom hire is common |
| Bulking agent | $0–30/wet tonne | Often free (chips from utility trimmings); can be negative cost (gate fees) |
| Labor | 0.5–2 h per windrow per week during active phase | Scales with turning frequency |
| Testing | $100–400/yr | Nutrients + stability; cheap insurance |
| Additives & amendments | $0–80/t treated | Optional — only where chemistry demands it (see Additives & Inoculants) |
| Permitting (where required) | Highly variable | Small on-farm operations often exempt; check thresholds |
Indicative US figures in USD; verify with local contractors and your state/provincial program. Published farm-budget studies put on-farm windrow composting in the rough range of $8–30 per wet tonne processed depending on scale and capital assumptions.
Equipment & infrastructure choices
- Loader-only turning: fine to ~500–1,000 t/yr; slower, less thorough mixing, more compaction risk.
- Tractor-mounted turner: the workhorse for 1,000–10,000 t/yr; needs 60–100+ PTO hp depending on width.
- Self-propelled turners: for large operations and commercial yards; fastest and most uniform.
- ASP retrofit: blower + pipe + timer ($3k–15k per pad) replaces turning labor; excellent where odor or labor is the binding constraint.
- Water: a 2" pump and hose or a sprinkler setup for re-wetting; water is the most-underrated cost/limiter in dry climates.
The value side
On-farm value
- Fertilizer displacement (modest — see N availability)
- Soil-water benefits → yield resilience (see Benefits)
- Reduced hauling volume vs raw manure (2×–4× mass reduction typical)
- Avoided costs: bedding purchase, manure-storage capacity, permit friction
- Mortality management alternative (where legal)
Market value
- Agronomic-grade bulk: $5–25/tonne at the gate, often spread-cost only
- Landscape/mulch grade (screened): $20–60/yd³
- Bagged retail (screened, tested, branded): $100–400/tonne equivalent
- Vermicompost/tea inputs: niche premium markets
- Certified-organic compliance adds market access (with NOP documentation)
Markets and pricing
Selling compost is a materials-handling business with a marketing problem: buyers need consistent spec, moisture, cleanliness, and documentation. The ladder:
- Give/spread on-farm: default; value is soil benefit and avoided disposal.
- Bulk agronomic sales to neighbors: price near spreading cost; volume outlet.
- Screened landscape grade: requires screening, testing (e.g., STA), and consistency; margin appears here.
- Bagged/branded retail: requires capital, marketing, and QA — usually cooperative or off-farm partner territory.
Worked cost scenario: 200-cow dairy
A simplified, illustrative monthly ledger — every farm differs; this is the arithmetic shape, not your number:
| Item | Assumption | Monthly (indicative) |
|---|---|---|
| Income/avoided costs | ||
| Bedding displaced | 2 of 12 months replaced by compost (sawdust $35/t × 40 t) | +$233 |
| Hauling avoided | 3 loads/mo manure at $120 delivered previously | +$360 |
| Fertilizer credit | ~10 t/ha × ~10 ha at $40/t N-equivalent | +$400 |
| Sale revenue | 20 t/mo screened at $15/t | +$300 |
| Subtotal benefit | +$1,293 | |
| Costs | ||
| Bulking agent (chips) | 10 t/mo at $20/t | $200 |
| Pad amortization | $30k over 10 yr | $250 |
| Turner (amortized) | $40k over 7 yr | $476 |
| Labor | 0.75 h/day at $25/h | $565 |
| Testing & misc | Annual panel + fuel | $110 |
| Subtotal cost | $1,601 | |
| Net per month | −$308 (−19%) | |
Two reads of this picture matter: first, the ledger is usually negative as a stand-alone line item. Second, skim the row where viability flips: loader-only turning (drop the turner), existing pad (lose most amortization), or a garden-center market (sale price triples) all swing this scenario to break-even or positive. Composting earns its keep through avoided costs and system resilience — which is why agricultural analysts price it against the alternatives, not against zero.
Business models seen on farms
- Cost-center model: compost only what the farm needs; minimize inputs; simple and robust.
- Gate-fee model: accept off-farm organics (yard, stall waste, food) for a fee; converts other people's disposal problem into your feedstock economics; requires permits and contaminant management.
- Product model: certified, tested, branded compost for horticulture; highest margin, highest demands (QA, packaging, liability).
- Service model: custom composting for other farms (you own the process, they keep the product), or land-application services.
Regulatory & policy costs
- Exemptions: most jurisdictions exempt small on-farm composting of farm-generated manure/residues (thresholds commonly 1,000–5,000 yd³ or by acreage).
- Permits: accepting off-farm feedstocks (especially food waste) typically triggers registration/permits, pad and setback standards, and reporting.
- Cost-share: USDA-NRCS Composting Facility (Code 317) and similar EQIP-style programs in the US, plus provincial/state programs elsewhere, frequently fund pads, turners, and covers.
- Carbon/nutrient trading: in some regions, avoided-GHG and water-quality credits add revenue (documentation-heavy).